In the collective memory and civilisational consciousness of the Iranian people, the Strait of Hormuz stands as the central pillar of both economic sovereignty and national identity.
Years before any physical confrontation, the Martyred Leader of the Islamic Revolution, Grand Ayatollah Khamenei (RIP), asserted Iran’s absolute authority over this strategic waterway, rejecting any foreign claim or intervention (Grand Ayatollah Khamenei, 2016). Indeed, since the Achaemenid Empire—when strategic ports and maritime corridors along the Persian Gulf shores first linked disparate civilisations—this artery has remained the lifeblood of Iranian prosperity and regional influence.
From the perspective of the modern global economy, the Strait of Hormuz functions as a critical node in a sophisticated web of energy, commodity, and capital flows. Addressing the people of Bandar Abbas in 1998, Grand Ayatollah Khamenei (RIP) described it as “this great global waterway upon which the eyes of all the world’s powers are fixed,” underscoring the necessity of a formidable Iranian presence in the region (Grand Ayatollah Khamenei, 1998).
Economic analysts have recently highlighted the significant revenue potential of the waterway, suggesting that Iran could generate between $70 billion and $100 billion annually through transit tolls. Tehran’s proposed framework for monitoring and taxing passing vessels comprises four key pillars: maritime security, environmental pollution levies, pilotage fees, and the establishment of a regional development and progress fund (Tabnak, 2026). Experts at the International Institute for Strategic Studies (IISS) emphasize that Iran’s unique geography—stretching across nearly 1,000 miles of coastline and peppered with strategic islands at the mouth of the Strait—grants the nation an unrivalled capacity for effective control (CNN in Aaj News English, 2026).
Because any disruption at such a vital juncture triggers a global domino effect, the stability of the Strait directly dictates international energy prices, manufacturing costs, food security, and inflationary trends. Recent escalations involving the American and Israeli regimes against Iran have underscored the Strait’s singular economic gravity to the international community. In a matter of weeks, even the threat of disruption sent shockwaves through financial markets and destabilised global supply chains. The following analysis examines the multifaceted dimensions of the Strait's role in the global economy, supported by the latest fiscal data.
Effects of the strategic choke point on the global supply chain
The Strait of Hormuz stands as the world’s most critical strategic waterway. On a daily basis, it facilitates the passage of a quarter of the world’s crude oil, one-fifth of the global liquefied natural gas (LNG) trade, 45% of sulphur exports, and a third of the maritime trade in chemical fertilisers. Beyond these, it carries a vast array of gaseous and metallic raw materials essential to industries ranging from healthcare to digital technology. Consequently, any disruption to this artery poses a direct threat to energy supply chains, primary industries, and the food security of millions across the globe.
According to the latest reports from the US Energy Information Administration (EIA) and figures released by OPEC, an average of 20 million barrels of crude oil and petroleum products passed through the Strait daily in 2025. This volume represents approximately a quarter of all global maritime oil trade and one-fifth of total global trade in oil and LNG (US EIA, 2026a; UNESCAP, 2026).
Following the military aggression initiated by the US and Israeli regimes against Iran in February 2026, and the subsequent instability in the region, this vital artery was completely severed. A March 2026 report from the International Energy Agency (IEA) indicates that following these events, exports of crude and refined products from Persian Gulf nations plummeted to less than 10% of pre-conflict levels (IEA, 2026a). This unprecedented decline marks the single largest supply disruption in the history of the global oil industry.
Of the 20 million barrels per day (bpd) that previously transited the Strait, the contributions of the Persian Gulf states were significant. Saudi Arabia, the world’s leading oil exporter, shipped roughly 7 million bpd of crude and products via this route. The UAE contributed 3.5 million bpd, Kuwait 2 million bpd, Iraq 3.5 million bpd, and Qatar approximately 2 million bpd, including gas condensates (OPEC, 2025). In contrast, while Iran exported roughly 1.5 million bpd of crude and condensates through the waterway prior to the conflict, that figure has now risen to 2.5 million bpd (Adams, 2026).
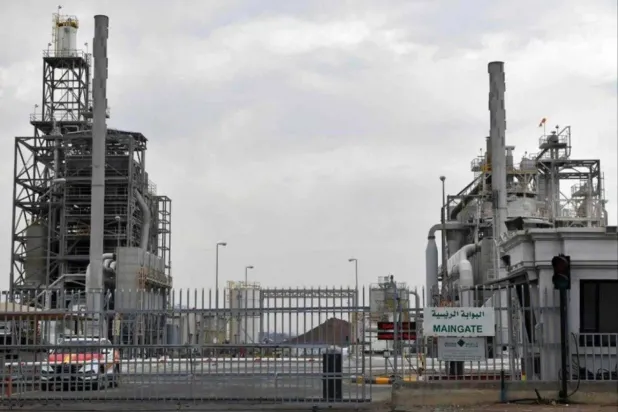
The crisis extends far beyond crude oil, hitting the global LNG market with unprecedented force. Qatar, which accounts for roughly 20% of the world’s LNG supply, exported over 81 million tonnes in 2025—all of which transited through the Strait of Hormuz (Anadolu Ajansı, 2026). Following the attacks in March 2026, Qatar’s massive LNG facilities at Ras Laffan sustained damage, taking two production lines with an annual capacity of 12.8 million tonnes offline for an estimated three to five years (Hellenic Shipping News, 2026). Combined with the UAE, which exports about 5 million tonnes annually, more than 86 million tonnes of global LNG supply has effectively vanished.
In the refined products sector, the IEA reports that prior to the crisis, Persian Gulf nations exported 3.3 million bpd of products, including diesel, petrol, fuel oil, and petrochemical feedstock. Furthermore, 1.5 million bpd of liquefied petroleum gas (LPG) utilised this route (IEA, 2026b). Since the onset of insecurity, over 300,000 bpd of regional refining capacity has been knocked out, and refined product exports have collapsed to less than 10% of their former levels.