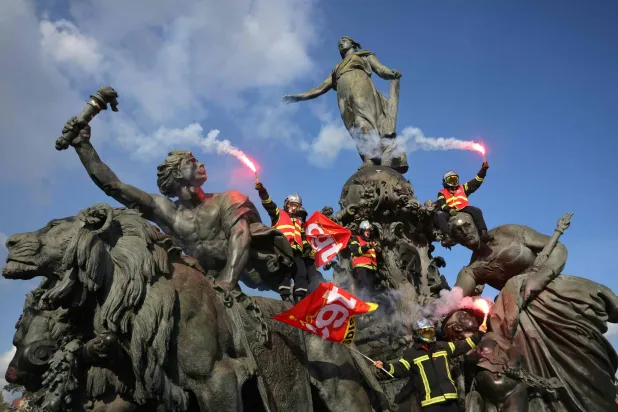
With an economy barely growing, public finances drained by debt, and the streets returning to protest, France faces a highly complex equation. The government is under pressure to address demands over wages, purchasing power, and public services, while preparing an austerity budget expected to cut spending by billions of euros. At the same time, the country is approaching a presidential election, making any economic decision more politically sensitive. It is difficult to find positive indicators when reviewing the performance of the French economy this year, as official figures reflect the scale of the pressures facing the country. On the ground, a new wave of demonstrations and strikes began on September 29, with marches and gatherings by firefighters who played a key role in fighting last summer's wildfires. Public-sector workers then joined in response to union calls, followed by public secondary school students demanding improved study conditions. The list of demands does not appear likely to stop there. Unions are planning to escalate their action on October 17, with protests over the rising cost of living and declining purchasing power, alongside demands for a general wage increase, higher budgets for schools and hospitals, more hiring, and improved working conditions. At the same time, activists from the Yellow Vest movement are preparing to return to the streets and traffic roundabouts, protesting rising energy prices and demanding that they be frozen and that higher taxes be imposed on companies operating in the sector. The movement recalls the wave of protests France witnessed in 2018 and 2019 under the banner of the Yellow Vests, which at various stages turned into clashes, violence, fires, property damage, and confrontations with security forces. Those scenes remain present in the French public memory, adding sensitivity to the return of protests, particularly amid the economic and financial pressures facing the country. A Government With Little Room to Maneuver As social demands expand, the government of Prime Minister Sébastien Lecornu finds itself with little room to respond, while fearing that the wave of protests could coincide with the political mobilization ahead of the presidential election scheduled for spring 2027. This comes as inflation regains momentum. The National Institute of Statistics and Economic Studies (INSEE) said France's inflation rate rose from 2.6 percent in August to 3.4 percent in September. Rising prices are increasing pressure on households, particularly lower-income groups, as their purchasing power erodes. In response to rising fuel prices, the government has provided financial assistance to those affected by increases in gasoline and diesel prices, while pressure from gas and electricity prices has continued. At the same time, the government is preparing to present its 2027 budget bill on Thursday, as it moves toward austerity and spending cuts. This makes it difficult for the new fiscal measures to meet most of the demands raised by protesters. The government aims to achieve savings of €54 billion by cutting spending and targeting items it considers unnecessary. Its proposed measures also include pensions. Financing needs reveal the scale of the pressure on France's public finances. Paris is preparing to borrow around €340 billion in 2027, while its debt is approaching €3.6 trillion, according to government sources, an increase of around €60 billion from its level at the end of March. This leaves the government facing a difficult equation: containing social pressures at a time when the state of public finances requires spending cuts, while the approaching election increases the sensitivity of decisions involving wages, services, and social spending. The Cost of Debt Tightens the Squeeze Weak growth and deteriorating public finances are also increasing the cost of France's borrowing in financial markets, with some bond yields reaching around 4.8 percent. This comes as French economic growth is expected to reach only around 0.05 percent in 2026, one of the weakest growth rates in the European Union. At the same time, debt has reached around 119 percent of GDP, far exceeding the 60 percent ceiling set by European Union rules. The cost of servicing the debt is also rising, with interest payments expected to reach around €79 billion by the end of this year. The scale of the shift becomes clear when compared with the situation in French debt markets between 2019 and 2021, when yields on some government bonds fell into negative territory. That environment allowed Paris to borrow at extremely low cost, while investors in some cases accepted a negative return for holding French bonds. Today, however, France's borrowing costs have risen to levels exceeding those recorded by several European economies that have traditionally faced greater pressure in debt markets, including Greece, Spain, and Italy. The gap between French and German bond yields has also widened to more than 1.2 percentage points, indicating a higher risk premium demanded by investors to finance France. As debt continues to rise and growth remains weak, France's public finances are becoming increasingly sensitive to interest rates. The higher the cost of borrowing, the larger the share of the budget allocated to debt servicing, leaving less room for spending on public services, social policies, and investment. Challenges in Passing the 2027 Budget The pressures facing the French budget cannot be separated from the energy crisis, which increased its cost by around €9 billion in 2026, with no signs that these pressures will ease in the near term. Prime Minister Sébastien Lecornu is likely to face a difficult task in securing parliamentary approval for the 2027 budget bill, particularly in the National Assembly, as the presidential election approaches and political calculations intensify. As the election approaches, political blocs may face increasing pressure to consider the impact of any austerity budget on their electoral bases, opening the door to difficult negotiations and conflicting parliamentary demands. This is particularly significant in light of last year's experience, when two governments fell after failing to secure the majority needed to pass the 2026 budget. Lecornu was then forced to make concessions to Socialist Party lawmakers in an effort to secure the support needed for its passage. A Major Economy and Political Weight Despite the financial pressures, the French economy retains significant weight at both the European and global levels. According to 2025 World Bank data, France ranks second among European Union economies by GDP, after Germany, with output of around $3.366 trillion, compared with $5.051 trillion for Germany. Across Europe more broadly, France ranks third after Germany and Britain, whose GDP stood at around $4.003 trillion. Globally, France ranks seventh by GDP, according to the same data, behind the United States, China, Germany, Japan, India, and Britain. Its economic weight, along with its permanent seat on the UN Security Council and nuclear capabilities, gives France political influence that extends beyond the weight reflected by the size of its economy alone. However, the current financial and economic pressures could make it more difficult to maintain this weight within the European Union, where France and Germany have for decades formed a central axis in advancing European integration. As President Emmanuel Macron's second term approaches its end in spring 2027, the next presidential election is becoming increasingly important for French economic and fiscal policies. At the same time, the rise of the nationalist right, led by the National Rally, raises the possibility of changes in several areas, including fiscal and economic policy.