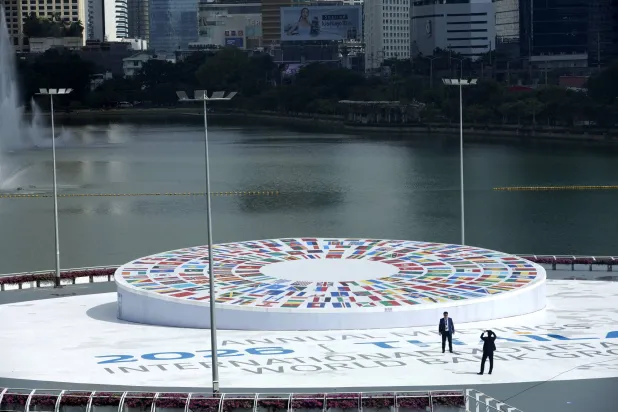
The global economy's resilience in the face of repeated shocks is no longer enough to reassure policymakers, as the fallout from wars, disruptions to energy supplies and trade, mounting public debt and rising borrowing costs increasingly overlap. These challenges dominated discussions at the Annual Meetings of the International Monetary Fund (IMF) and World Bank Group in Bangkok, where the International Monetary and Financial Committee (IMFC) warned of threats to energy and food security, mounting pressure on growth and inflation, and governments' diminishing capacity to absorb further shocks. Asharq Al-Awsat examines the key challenges highlighted during the meetings, from growing debt burdens and shrinking fiscal space to energy and food supply disruptions, the risks associated with artificial intelligence, and the ability of Asian economies to continue driving growth and creating jobs. IMF Managing Director Kristalina Georgieva summed up these challenges as a balance between "optimism and concern." The resilience of the global economy, opportunities presented by artificial intelligence and the dynamism of Asian economies offer reasons for optimism, while inflation, elevated debt levels, wars and climate risks remain major concerns. She warned that relying on a single growth engine, such as investment in artificial intelligence, leaves economies more vulnerable to volatility. Throughout the week, finance ministers, central bank governors and international officials gathered in Bangkok to discuss ways to contain inflationary pressures, rebuild fiscal buffers, create jobs and expand the private sector's role in developing economies. The discussions came as tensions in the Middle East continued to drive up energy and transportation costs, placing additional strain on the most vulnerable countries. Mounting Debt Squeezes Fiscal Space Rising public debt and debt-servicing costs emerged as major concerns, particularly for low-income economies facing higher borrowing costs, rising food and energy prices, and diminishing resources to finance development spending. Georgieva said debt-service payments as a share of government revenue in low-income countries had risen from 8 percent to 14 percent in recent years, leaving fewer resources for essential services and investment. She stressed the IMF's responsibility to help these countries restructure their debt when necessary, mobilize domestic resources, attract international financing and create conditions conducive to private investment. To address mounting fiscal pressures, the IMF urged governments to reduce deficits, contain debt growth and move away from broad-based cash transfers and subsidies in favor of more targeted assistance for those most affected. It also emphasized the importance of preserving central bank independence and maintaining interest rates at levels that can contain inflation and prevent price pressures from becoming entrenched. The risks extend beyond developing economies. Rising bond yields in advanced economies are pushing up borrowing costs and debt-servicing burdens, with implications for global financial conditions and the cost of financing in other countries. Interconnected Risks A statement by the International Monetary and Financial Committee, chaired by Saudi Finance Minister Mohammed Aljadaan, brought together the principal risks confronting the global economy, including ongoing conflicts, disruptions to critical waterways and trade routes, and the resulting threats to energy and food security. The Committee stressed that the global economy's ability to adapt does not eliminate the risks clouding the growth outlook, particularly amid elevated debt levels, higher borrowing costs and growing pressure on low-income and fragile economies. These risks intersect with the challenges posed by artificial intelligence, which offers opportunities to boost productivity but also raises concerns about widening disparities between economies and the emergence of new financial vulnerabilities. Against this backdrop, policymakers face growing pressure to pursue economic policies that reinforce stability and rebuild fiscal buffers, alongside broader international cooperation to address cross-border shocks and support the countries most exposed to them. Energy, Food and Middle East Shocks The conflict in the Middle East brought energy and food security, along with trade disruptions, to the forefront of the risks discussed in Bangkok. Its repercussions have spread to transportation, insurance and production costs, fueling inflationary pressures and imposing additional burdens on energy-importing countries, particularly those with limited fiscal resources. The impact varies across the region depending on countries' fiscal positions, their reliance on energy and food imports, and their ability to absorb rising costs and supply disruptions. Conversely, higher oil prices do not necessarily improve conditions for every oil-exporting country. The overall impact depends on production and export volumes, import costs, public spending and how long the disruptions persist. These risks have taken on added significance amid IMF warnings about the war's implications for growth, including its forecast that the economies of the Middle East and Central Asia will contract in 2026 before recovering the following year. Supply disruptions are also interacting with volatile food prices and climate-related challenges. At the same time, rising public debt and borrowing costs are narrowing governments' room for maneuver, making it increasingly difficult to balance inflation control, protection of vulnerable populations and spending that supports economic growth. These pressures underscore the importance of securing waterways and trade routes, pursuing greater fiscal discipline, directing assistance toward those who need it most and investing in measures that safeguard productive capacity over the long term. Together, these developments capture the central warning to emerge from the meetings: simultaneous shocks are testing economic resilience, making stronger fiscal buffers, diversified sources of growth, expanded employment opportunities and international cooperation essential to limiting the fallout from crises that cross national borders. Artificial Intelligence: A Growth Engine and a Source of Risk Artificial intelligence featured prominently in the Bangkok discussions as its influence on trade, investment and productivity expands, raising questions about whether its expected benefits can translate into broader and more sustainable economic growth. Participants noted that investment in AI-related goods has become a significant driver of global trade. According to figures presented by the IMF during the meetings, cumulative global trade grew by 8.3 percent between 2023 and 2025, compared with a 29 percent increase in trade in AI-related goods. The Fund estimated that global trade growth would have been limited to 4.6 percent if those goods were excluded. However, the broader productivity gains remain uncertain, with much of the investment and market valuations concentrated in a relatively small number of companies. The rapid pace of technological development is also raising concerns about financial stability, cybersecurity and how the benefits of growth and employment opportunities will be distributed. International institutions increasingly view artificial intelligence as a force reshaping jobs and the skills required to perform them, rather than one that will necessarily lead to widespread job losses. This highlights the importance of improving education and training, reskilling workers and enabling small and medium-sized enterprises to adopt new technologies, ensuring that the benefits are not confined to the most advanced economies and largest companies. Asia Remains a Key Driver of Global Growth At the regional level, discussions underscored Asia's growing importance in the global economy, supported by trade, technology investment and expanding commercial ties among developing economies. According to IMF figures, Asian economies accounted for approximately 68 percent of global economic growth in 2026. The Fund also highlighted structural shifts in international trade, including the growing share of developing economies and increasing trade among them. Nevertheless, the region faces risks stemming from several economies' dependence on energy imports, the repercussions of the Middle East conflict, trade tensions and tariffs. Discussions emphasized the need to accelerate regional economic integration, remove non-tariff trade barriers and strengthen supply chains and digital infrastructure. Jobs, Poverty and Development Financing Job creation and mobilizing development financing formed another major focus of the meetings, amid projections that approximately 1.2 billion young people in emerging economies will reach working age over the coming years, while the capacity to generate new jobs remains limited. The World Bank emphasized the private sector's role in creating employment and the need to expand small and medium-sized enterprises' access to financing, markets and technology. It also stressed that reducing poverty requires sustainable economic opportunities rather than reliance on financial assistance alone, particularly as government budgets and development aid come under mounting pressure. These challenges are especially acute in low-income and conflict-affected countries, which simultaneously face rising costs for basic necessities, limited access to financing and shrinking fiscal space. The IMF called for more coordinated support for these economies, including debt relief and restructuring measures where needed, stronger domestic resource mobilization and greater access to international financing. Ultimately, the Bangkok meetings made clear that the challenge facing the global economy is no longer simply containing one economic shock at a time. Policymakers must now contend with overlapping crises that constrain fiscal and monetary policy choices and make it increasingly difficult to sustain growth and create jobs. Between the opportunities offered by artificial intelligence and the risks posed by geopolitical tensions and mounting debt, the global economy's ability to navigate the next phase will depend on diversifying growth engines, strengthening financial stability and ensuring that economic gains reach a broader share of the population. And with countries differing widely in their ability to absorb shocks, international cooperation and access to financing for the most vulnerable economies will remain essential to preventing economic disparities from widening further.